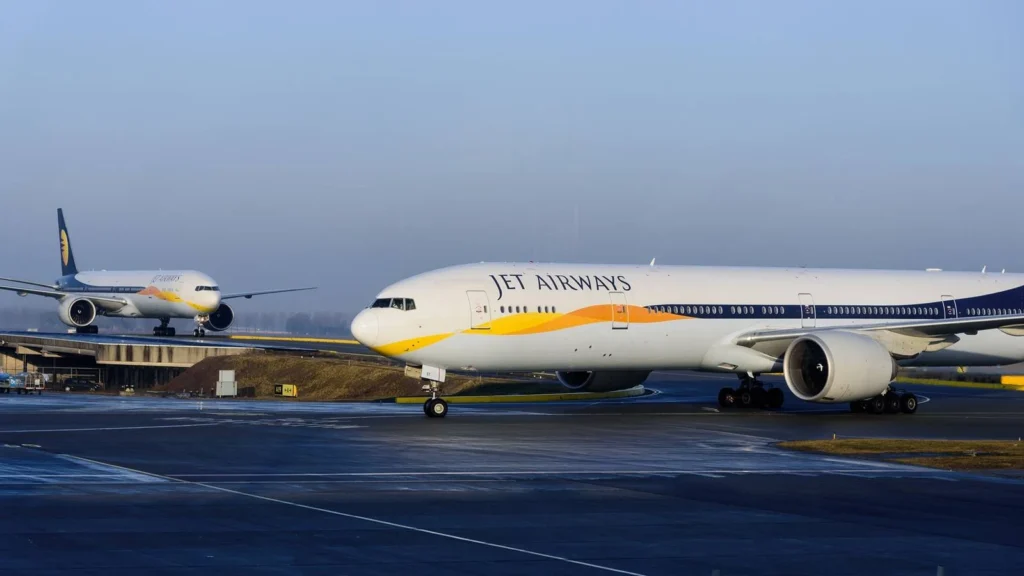
Jet Airways’ legal dispute with Boeing has renewed attention on unpaid ticket claims affecting Indian travel agents and former passengers. However, proceedings involving the aircraft manufacturer do not establish a refund timetable for customers or agencies.
The airline’s liquidator, Satish Kumar Gupta, brought the appeal listed before the National Company Law Appellate Tribunal on 3 November 2026. For claimants, the central issue extends beyond whether the airline eventually recovers money.
Any distribution depends on available funds, creditor priorities and applicable orders. An admitted ticket claim therefore cannot be treated as a guaranteed repayment.
Boeing Proceedings Keep Recovery Questions Open
The tribunal’s listing identifies Company Appeal (AT) (Insolvency) No. 2101 of 2026, involving Jet Airways and The Boeing Company. The matter appeared before Court IV in New Delhi on 3 November.
A scheduled case does not, by itself, confirm the outcome of proceedings. It also provides no assurance about eventual recoveries or payments to individual creditors.
For travel businesses awaiting money, this distinction shapes how developments should be communicated. Litigation may concern funds sought for the airline’s estate, while ticket refunds involve a separate distribution process.
Consequently, agencies cannot calculate customer repayments from the existence of the Boeing appeal alone.
Travel Agencies Appear In Creditor Records
Published creditor records demonstrate how the airline’s financial collapse reached businesses selling flights to travellers.
Historical entries identify Travel Dynamics India with ₹1,41,846 claimed and admitted. Travel Masters (Mumbai) appears with ₹1,48,100 claimed and admitted.
Other entries show substantial differences between submitted claims and recognised amounts.
Travair Connections claimed ₹8,54,803, while ₹1,83,200 was admitted. Travel Consol submitted ₹19,80,451, compared with an admitted amount of ₹2,80,339.
Meanwhile, Travel Spirit International claimed ₹1,63,706, with ₹27,314 admitted.
These historical figures illustrate why agencies need to examine their individual records. They do not establish current outstanding balances or confirm whether subsequent payments occurred.
A claim’s original value, admitted value and remaining unpaid balance may represent different amounts.
Claim Admission Does Not Guarantee Payment
Admission recognises a claim within the insolvency or liquidation process. It does not establish when payment will arrive or what proportion will be recovered.
The liquidation guidance described in the supplied material places most operational creditors, including ticket-refund claimants, within Category 6.
Their position means several other categories rank ahead of them when available proceeds are distributed.
For travel agencies, an admitted amount should therefore remain distinct from money received. Treating the two as interchangeable could create inaccurate customer expectations.
Similarly, passengers should not interpret proceedings involving Boeing as approval of their personal refund requests.
The practical question concerns the money ultimately available for the relevant creditor category, rather than a headline litigation figure.
Creditor Priorities Shape Recovery Prospects
India’s liquidation framework establishes an order for distributing proceeds among different stakeholders.
Insolvency resolution and liquidation costs rank first. Other categories include specified workmen’s dues, qualifying secured debts, employee dues and unsecured financial debts.
Remaining debts and dues fall further down the hierarchy, ahead of preference shareholders and equity holders.
This structure explains why a recovery for an airline does not automatically translate into equivalent payments for ticket holders.
Even if additional money becomes available, its effect depends on higher-ranking obligations and the distribution arrangements that apply.
No individual agency’s repayment percentage can be calculated solely from the appeal listing or its historical admitted claim.
Booking Records Matter For Passengers
A passenger’s relationship with a travel agent requires separate examination from the agency’s position in the airline’s liquidation.
Useful records include the booking confirmation, payment receipt, refund correspondence and any claim acknowledgement.
Passengers seeking clarity can request a written explanation identifying who submitted the claim and whose name appears in creditor records.
Where an agency submitted a claim, its records should explain how the customer’s booking relates to that submission.
However, creditor registers cannot resolve every underlying transaction. They identify claimants and amounts without necessarily explaining each customer agreement.
Clear documentation helps agencies provide precise updates while distinguishing airline recoveries from their own customer arrangements.
Travel Businesses Await Distribution Clarity
For agencies managing older refund cases, three figures remain especially important: the booking payment, admitted claim and money subsequently received.
Keeping these amounts separate supports accurate accounting and clearer communication with customers.
Updates about asset sales, employee entitlements or other creditor groups should also be assessed carefully. They do not automatically establish progress on ticket refunds.
The next meaningful development would be a verified change affecting an agency’s claim or distribution position.
Until repayment arrangements are formally established, the Boeing dispute remains a recovery issue with uncertain consequences for individual travel creditors.
For more travel news like this, keep reading Global Travel Wire